Business Interruption Insurance in Ohio: What Happens to Revenue After a Covered Loss
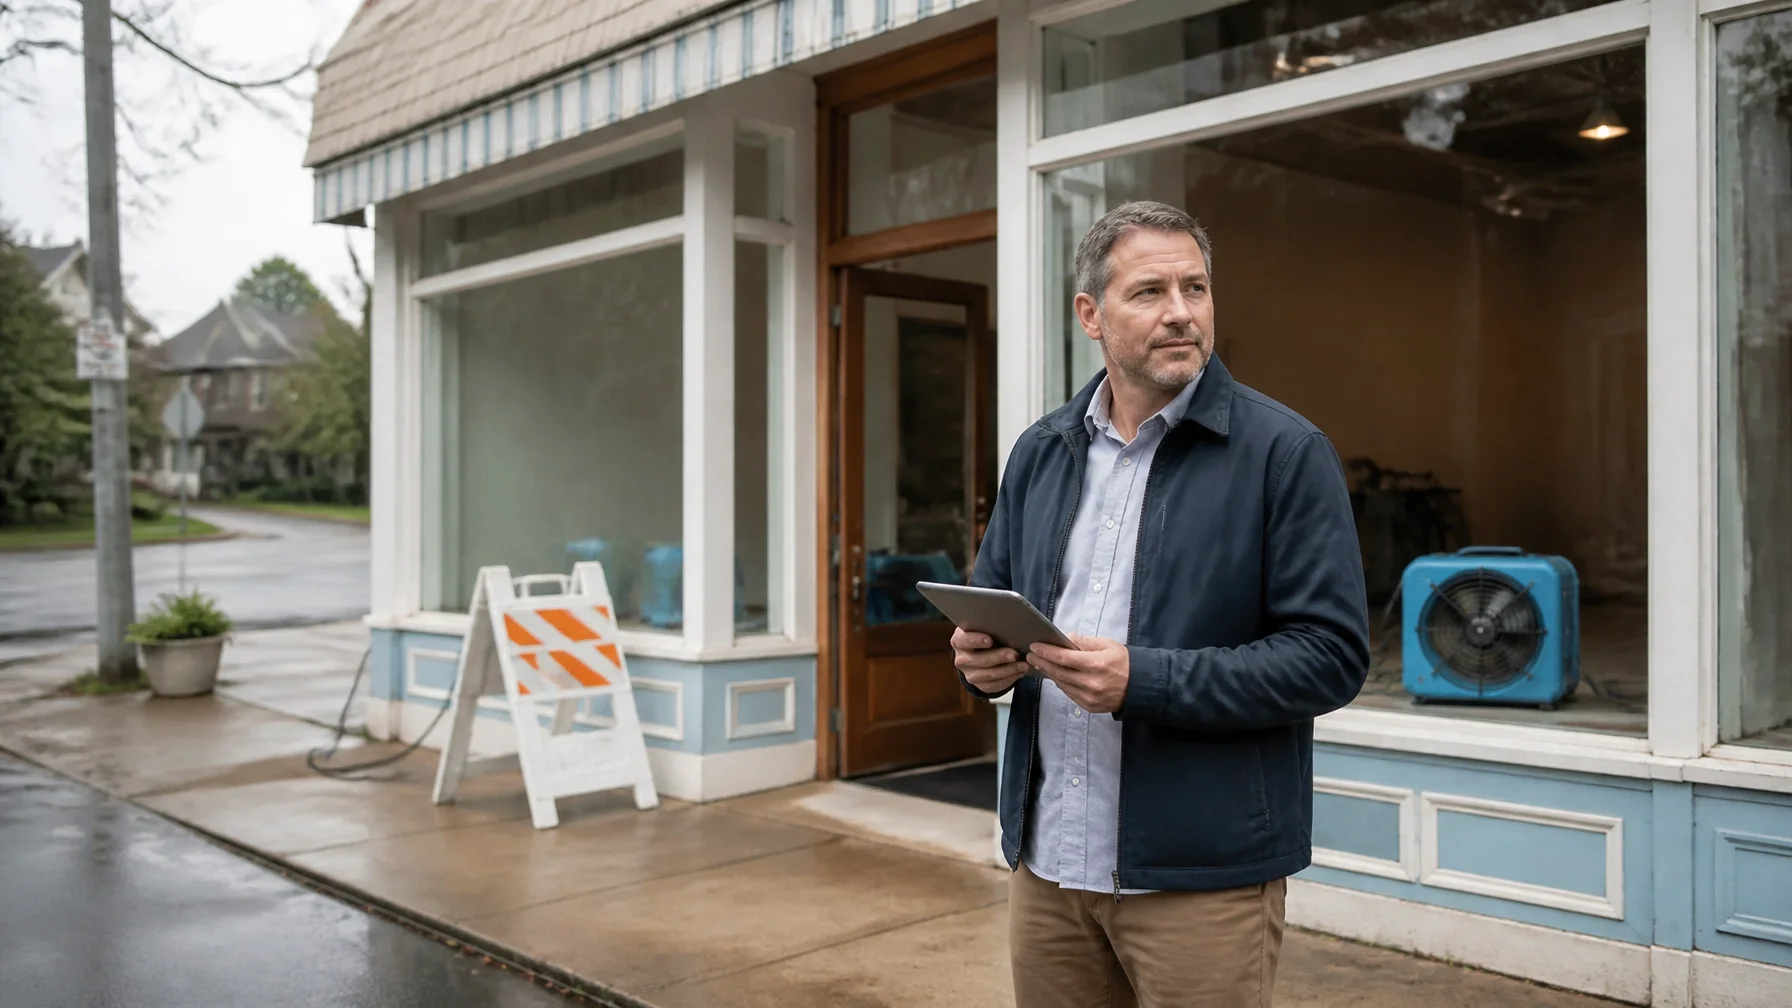
A water pipe breaks overnight in a Clintonville storefront. By morning, the ceiling has collapsed, inventory is damaged, and the business must close while repairs begin. The owner still has rent, payroll, loan payments, utilities, and vendor obligations, but regular sales have stopped.
Property insurance may address covered damage to the building, equipment, inventory, or business personal property. It does not necessarily address the income your business cannot earn during the shutdown. That is where business interruption coverage, often called business income coverage, may become important.
For an Ohio small business that depends on a physical location or steady operations, this coverage can help you evaluate whether your policy fits your business.
What business interruption insurance in Ohio is designed to do
Business interruption insurance is generally designed to help replace income and certain continuing expenses when a covered event causes a necessary suspension of business operations. The event usually must involve direct physical damage from a covered cause of loss under the applicable commercial property policy, such as a covered fire, windstorm, or water loss, depending on the policy terms, exclusions, and the circumstances of the claim.
The purpose is not to reimburse every dollar of sales. Business income coverage generally considers the income your business would reasonably have earned, along with eligible continuing expenses. The calculation depends on policy language and financial records.
The calculation may consider:
Net income the business would have earned
Continuing normal operating expenses
The business’s prior financial performance
Expected trends and seasonal changes
The time required to repair or replace damaged property
The applicable policy limit and coverage conditions
Business income coverage is generally not a substitute for commercial property insurance. It works alongside property coverage, subject to the policy’s terms, limits, exclusions, and claim requirements.
For a broader overview of commercial coverage, review our small-business guide to commercial insurance in Ohio.
What the coverage may pay for, and what it may not
Protection depends on policy form and endorsements. Some policies include business income with extra expense; others may provide narrower protection or limits.
Depending on the policy, covered business income may include:
Lost net income: Income the business would have earned if the covered loss had not occurred, after considering relevant expenses.
Continuing payroll: Wages or salaries that remain necessary during the interruption. The amount and duration may depend on the policy.
Rent or mortgage obligations: Payments that continue while the business cannot use the damaged premises.
Utilities and ordinary expenses: Certain expenses may continue even when operations are limited or stopped.
Loan, lease, or tax obligations: Some continuing financial obligations may be included, subject to the policy.
Temporary relocation costs: Expenses associated with moving operations to another location may be covered when the policy includes applicable extra expense protection.
Extra expenses to reduce the interruption: Costs that help the business continue operating or reopen sooner may be covered if they meet the policy’s requirements.
A business may also have access to extended business income coverage. This may continue for a limited period after repairs and reopening, which may matter for a Dublin restaurant rebuilding customer traffic or a contractor reestablishing work.
Business interruption coverage may not respond to every type of disruption. Common limitations can involve:
Losses without qualifying physical damage
Causes of loss excluded by the property policy
Flood, earthquake, cyber events, or other excluded causes, depending on the policy
A closure that does not meet the policy’s definition of suspension
Income beyond the selected coverage limit
Expenses that are not considered covered or continuing expenses
Delays unrelated to repairing covered physical damage
A policy may also have separate provisions for civil authority, utility interruption, or dependent property losses. These coverages can have different triggers, waiting periods, limits, and time restrictions.
The important point is simple. A business interruption claim is determined by the policy language and the facts of the loss, not by the name of the coverage alone.
Business Income, Extra Expense, and Other Coverage Explained
These coverages address different parts of a disruption.
Business income: This is generally the part that may address lost income and eligible continuing expenses after a covered loss suspends operations.
Extra expense: This may help pay additional costs that allow you to continue operating or reopen more quickly, subject to the policy.
Extended business income: This may continue for a limited period after reopening if income remains below the level the business would have reached without the loss.
Civil authority: This may apply when a government order prohibits access to your premises because of covered damage to nearby property. The requirements are typically different from standard business income coverage.
Property insurance: This generally addresses direct physical damage to covered buildings, inventory, equipment, furniture, or improvements. It does not automatically replace lost revenue.
A business may need more than one of these protections. The right combination depends on how your business earns money, what property it uses, and how much flexibility it has during a shutdown.
Limits, waiting periods, and restoration time
Three time and limit questions deserve attention.
The waiting period
Business income coverage may include a waiting period, sometimes called a time deductible. Coverage may not begin immediately when the physical damage occurs. The policy may specify a number of hours that must pass before eligible business income losses begin, and the waiting period may differ for certain coverages, such as utility interruption or civil authority.
The period of restoration
The period of restoration generally begins after a covered loss and continues while the damaged property is being repaired or replaced, subject to the policy’s definitions and conditions.
The restoration period can be affected by:
How quickly damage is assessed
Permit and inspection requirements
Contractor availability
Material and equipment delays
Whether the property can be repaired or must be rebuilt
The policy’s time limits and extensions
Whether the business could reasonably resume at another location
The restoration period may end when the property is repaired, replaced, or capable of being used for its intended purpose, rather than when revenue fully returns to normal.
The dollar limit
The limit should reflect more than one month of ordinary profit. Consider the time it could take to repair your location, replace specialized equipment, restore inventory, and rebuild customer activity. A small office may recover differently from a food-service business, retail shop, or trades company.
Keep income statements, sales records, payroll information, tax documents, budgets, contracts, and other relevant records organized and accessible. These records may help establish what the business would have earned and which expenses continued.
Who should consider it and what to ask before a loss
Business interruption coverage may be worth reviewing if your business depends on a physical location, specialized equipment, inventory, customer access, or a steady flow of appointments and orders.
This can include:
Retail stores and neighborhood shops
Restaurants, bakeries, and food-service businesses
Offices that depend on a leased commercial space
Contractors and trades businesses with tools, materials, or a workshop
Professional practices with a physical office
Wholesale, storage, and light manufacturing operations
Businesses that would need temporary space after a covered loss
Even an owner-operated business may have significant exposure through rent, equipment financing, software subscriptions, utilities, and customer commitments.
Before a loss, ask:
What specific events could stop our operations?
Would the policy require direct physical damage before business income coverage applies?
What expenses would continue if our location closed for several weeks?
Is payroll included, and for how long?
Does the policy include extra expense coverage?
Could we operate temporarily from another location?
What waiting period applies?
How is the period of restoration defined?
Is extended business income included?
How were our business income limits calculated?
Are seasonal changes or expected growth reflected in the limits?
Which records should we maintain for a potential claim?
Rise Insurance is an independent insurance agency. We help you review coverage options and communicate your business details to insurance carriers. The carrier issues the policy, evaluates covered claims, and determines claim payments or settlements under the policy terms.
If you operate a storefront, office, workshop, or other Ohio business location, you can review Rise Insurance commercial insurance services and consider whether your current business income protection matches your recovery needs. When you are ready, schedule a conversation with Rise Insurance to organize your questions and review your options without pressure.
